• 亿邦公众号
    • APP下载

阿里巴巴股价一度涨超4.5% 淘宝闪购业务表现改善带动净利润同比增长213%|财报解析

作者:郑雅 文章来源:亿邦动力

2026-11-20 13:32

作者:郑雅 文章来源:亿邦动力

2026-11-20 13:32

邦小白快读
EN
全文速览

总1财报核心数据

1.第三季度收入2715.19亿元同比增10%,净利润644.20亿元同比增213%,非公认会计准则净利润199.09亿元同比增92%,经营利润291.16亿元同比增443%,经调整EBITA326.36亿元同比增260%。

2.港股开盘后股价一度涨超4.5%,截至13时18分涨3.48%报83.350港元,成交额69.93亿元。

总2业务与实操干货

1.淘宝闪购和云业务经营改善带动经调整EBITA,阿里电商集团经调整EBITA388.51亿元同比增243%,即时零售收入587.57亿元同比增22%,非餐饮线上交易额同比增40%,前置仓在食品生鲜、日用百货发展迅速。

2.闲鱼日活跃用户同比增23%、支付订单同比增29%、实现多季度盈利,88VIP约6600万,新88VIP在双11期间ARPU同比显著上升;千问办公电商版连接淘宝天猫数据,可自动化店铺运营、业务分析、营销和客服。

总1营销与用户变化

1.新营销发展计划使相关补贴视作收入冲减项,销售和市场费用413.41亿元同比减37.83%,占收入15.2%,上年同期26.8%;淘宝闪购投入更高效。

2.88VIP约6600万,新88VIP双11 ARPU同比显著上升;闲鱼DAU同比增23%、支付订单增29%、多季度盈利。

总2渠道、定价与趋势

1.即时零售收入587.57亿元同比增22%,盒马线上线下强增长,与淘宝闪购深化合作并拓展多业态门店,为不同客群提供差异化产品;即时零售非餐饮线上交易额同比增40%,前置仓发展迅速。

2.蒋凡称国内消费环境承压、消费者支出意愿趋于保守,部分品类竞争激烈,刚需品类较可选消费品类趋势更好,平台将强化刚需品类日常销售竞争力;千问办公电商版可连接淘宝天猫数据,支持店铺运营、业务分析、营销和客服自动化。

总1平台政策与经营影响

1.新营销发展计划产生视作收入冲减项,中国电商客户管理收入同比减5%,不考虑该影响同口径同比增1%;销售和市场费用同比减37.83%,相关补贴改列收入冲减项。

2.淘宝闪购市场份额稳定、亏损继续收窄、UE环比改善,餐饮UE优化符合预期、比单价持续上涨,平台维持明年亏损缩小一半目标,并计划2029财年实现即时零售盈利。

总2机会、风险与可学习点

1.即时零售非餐饮线上交易额同比增40%,前置仓在食品生鲜、日用百货发展迅速;盒马与淘宝闪购深化合作并拓展多业态门店;B2B国际与国内业务整合,打通国内供给海外需求。

2.消费大环境承压、支出意愿保守、部分品类竞争激烈,刚需品类趋势更好;速卖通受欧盟海关改革影响收入下降,需关注跨境政策风险;千问办公电商版连接淘宝天猫数据,可自动化店铺运营、业务分析、营销和客服,并支持其他平台数据接入。

总1生产与设计需求

1.平头哥发布新一代AI芯片真武V900,阿里公布涵盖自研芯片、超节点架构、智能体原生云基础设施、AI模型及智能体的全面升级;云基础设施支出增加,AI相关产品收入179.18亿元,连续13个季度三位数同比增长。

2.即时零售前置仓在食品生鲜、日用百货等品类发展迅速,盒马线上线下均强增长,并通过多业态门店为不同客群提供差异化产品。

总2商业机会与数字化电商启示

1.即时零售非餐饮线上交易额同比增40%,即时零售收入587.57亿元同比增22%;全球批发收入142.60亿元同比增6%,跨境相关增值服务收入增长;B2B国际国内整合打通国内供给海外需求。

2.千问办公电商版直接连接淘宝与天猫数据,覆盖店铺运营、业务分析、营销和客服等商家工作全流程自动化,并将支持其他平台数据接入;速卖通受欧盟海关改革影响收入下降,提示跨境业务需关注政策变化。

总1行业趋势与新技术

1.AI云与算力服务收入609.73亿元同比增53%,外部客户收入同比增64%,外部客户经常性收入同比增67%;AI相关产品收入179.18亿元,连续13个季度三位数同比增长。

2.阿里全栈AI升级包括自研芯片真武V900、超节点架构、智能体原生云基础设施、AI模型及智能体;即时零售非餐饮线上交易额同比增40%,前置仓发展迅速,淘宝闪购UE环比改善。

总2客户痛点与解决方案

1.商家面临消费环境承压、支出意愿保守、部分品类竞争激烈,刚需品类较可选品类趋势更好;千问办公电商版连接淘宝天猫数据,提供店铺运营、业务分析、营销和客服自动化方案,并支持其他平台数据接入。

2.即时零售痛点落在亏损与UE,平台通过淘宝闪购运营效率提升、盒马多业态和深化合作改善;跨境方面速卖通受欧盟海关改革影响收入下降,B2B整合国际国内业务、打通国内供给海外需求形成协同方案。

总1平台运营与最新做法

1.新营销发展计划使相关补贴视作收入冲减项,销售和市场费用同比减37.83%,淘宝闪购投入更高效、运营效率提升;即时零售市场份额稳固,亏损继续收窄,UE环比改善,平台目标明年亏损缩小一半、2029财年盈利。

2.闲鱼DAU同比增23%、支付订单增29%、多季度盈利;88VIP约6600万,新88VIP双11 ARPU显著上升;千问办公电商版连接淘宝天猫数据,支持跨平台运营。

总2招商合作与风向规避

1.盒马与淘宝闪购深化合作、拓展多业态门店,为不同客群提供差异化产品;即时零售非餐饮线上交易额同比增40%,前置仓在食品生鲜、日用百货发展;B2B国际国内整合,打通国内供给海外需求。

2.消费大环境承压、支出意愿保守、部分品类竞争激烈,刚需品类较可选品类趋势更好,平台将强化刚需品类日常销售竞争力;速卖通受欧盟海关改革影响收入下降,需关注跨境政策风向。

总1产业新动向

1.AI云与算力服务收入609.73亿元同比增53%,外部客户经常性收入同比增67%,AI相关产品收入179.18亿元并连续13个季度三位数同比增长;全栈AI升级覆盖自研芯片真武V900、超节点架构、智能体原生云基础设施、AI模型及智能体。

2.即时零售收入587.57亿元同比增22%,非餐饮线上交易额同比增40%,前置仓发展迅速,淘宝闪购UE环比改善、亏损收窄,目标2029财年盈利。

总2商业模式与新问题

1.即时零售由淘宝闪购、盒马及天猫超市即时配送业务构成,盒马以线上线下和多业态门店提供差异化产品;闲鱼多季度盈利,88VIP约6600万且新会员双11 ARPU上升;B2B国际国内整合打通国内供给海外需求,千问办公电商版连接淘宝天猫数据并支持跨平台运营。

2.消费大环境承压、支出保守、部分品类竞争激烈,刚需品类较可选品类趋势更好;速卖通受欧盟海关改革影响收入下降,提示跨境政策法规变化对电商业务的风险。

声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Summary 1: Core financial data

1. Q3 revenue was RMB 271.519 billion, up 10% YoY; net profit was RMB 64.420 billion, up 213% YoY; non-GAAP net profit was RMB 19.909 billion, up 92% YoY; operating profit was RMB 29.116 billion, up 443% YoY; adjusted EBITA was RMB 32.636 billion, up 260% YoY.

2. After the Hong Kong market opened, the stock rose more than 4.5% at one point; as of 13:18 it was up 3.48% at HK$83.350, with turnover of RMB 6.993 billion.

Summary 2: Business and operational takeaways

1. Improved operations at Taobao Flash Sale and cloud helped drive adjusted EBITA; Alibaba's e-commerce group adjusted EBITA was RMB 38.851 billion, up 243% YoY; instant retail revenue was RMB 58.757 billion, up 22% YoY; non-food online transaction value rose 40% YoY; forward warehouses developed rapidly in fresh food and daily necessities.

2. Xianyu DAU rose 23% YoY, paid orders rose 29% YoY, and it achieved profitability for multiple quarters; 88VIP reached about 66 million; new 88VIP ARPU rose significantly YoY during Double 11; Qwen Office E-commerce Edition connects Taobao and Tmall data and can automate store operations, business analysis, marketing, and customer service.

Summary 1: Marketing and user changes

1. The new marketing development program treats related subsidies as revenue offsets; sales and marketing expenses were RMB 41.341 billion, down 37.83% YoY, accounting for 15.2% of revenue versus 26.8% a year earlier; Taobao Flash Sale investment became more efficient.

2. 88VIP reached about 66 million; new 88VIP ARPU rose significantly YoY during Double 11; Xianyu DAU rose 23% YoY, paid orders rose 29% YoY, and it was profitable for multiple quarters.

Summary 2: Channels, pricing, and trends

1. Instant retail revenue was RMB 58.757 billion, up 22% YoY; Freshippo saw strong online and offline growth, deepened cooperation with Taobao Flash Sale, and expanded multi-format stores to offer differentiated products to different customer groups; non-food online transaction value in instant retail rose 40% YoY; forward warehouses developed rapidly.

2. Jiang Fan said the domestic consumption environment is under pressure and consumers' willingness to spend is becoming more conservative; competition is intense in some categories; essential-demand categories are trending better than discretionary categories; the platform will strengthen the daily sales competitiveness of essential categories; Qwen Office E-commerce Edition can connect Taobao and Tmall data and support automation in store operations, business analysis, marketing, and customer service.

Summary 1: Platform policy and business impact

1. The new marketing development program generated items treated as revenue offsets; China e-commerce customer management revenue fell 5% YoY, or rose 1% YoY on a comparable basis excluding that impact; sales and marketing expenses fell 37.83% YoY, with related subsidies reclassified as revenue offsets.

2. Taobao Flash Sale's market share was stable, losses continued to narrow, and UE improved QoQ; food delivery UE optimization was in line with expectations, and average order value continued to rise; the platform maintained its goal of halving losses next year and plans to achieve instant retail profitability in fiscal 2029.

Summary 2: Opportunities, risks, and lessons

1. Non-food online transaction value in instant retail rose 40% YoY; forward warehouses developed rapidly in fresh food and daily necessities; Freshippo deepened cooperation with Taobao Flash Sale and expanded multi-format stores; B2B international and domestic businesses were integrated to connect domestic supply with overseas demand.

2. The broader consumption environment is under pressure, spending willingness is conservative, and competition is intense in some categories; essential categories are trending better; AliExpress revenue declined due to EU customs reform, requiring attention to cross-border policy risks; Qwen Office E-commerce Edition connects Taobao and Tmall data, can automate store operations, business analysis, marketing, and customer service, and supports data access from other platforms.

Summary 1: Production and design demand

1. T-Head released the new-generation AI chip Zhenwu V900; Alibaba announced a comprehensive upgrade covering self-developed chips, super-node architecture, agent-native cloud infrastructure, AI models, and agents; cloud infrastructure spending increased; AI-related product revenue was RMB 17.918 billion, growing triple digits YoY for 13 consecutive quarters.

2. Instant retail forward warehouses developed rapidly in categories such as fresh food and daily necessities; Freshippo grew strongly both online and offline and offered differentiated products to different customer groups through multi-format stores.

Summary 2: Business opportunities and digital e-commerce implications

1. Non-food online transaction value in instant retail rose 40% YoY; instant retail revenue was RMB 58.757 billion, up 22% YoY; global wholesale revenue was RMB 14.260 billion, up 6% YoY, with growth in cross-border-related value-added services; B2B international and domestic integration connected domestic supply with overseas demand.

2. Qwen Office E-commerce Edition directly connects Taobao and Tmall data, covering automation across the full merchant workflow including store operations, business analysis, marketing, and customer service, and will support data access from other platforms; AliExpress revenue declined due to EU customs reform, indicating that cross-border businesses need to monitor policy changes.

Summary 1: Industry trends and new technologies

1. AI cloud and computing power service revenue was RMB 60.973 billion, up 53% YoY; external customer revenue rose 64% YoY; external customer recurring revenue rose 67% YoY; AI-related product revenue was RMB 17.918 billion, growing triple digits YoY for 13 consecutive quarters.

2. Alibaba's full-stack AI upgrade includes the self-developed chip Zhenwu V900, super-node architecture, agent-native cloud infrastructure, AI models, and agents; non-food online transaction value in instant retail rose 40% YoY; forward warehouses developed rapidly; Taobao Flash Sale UE improved QoQ.

Summary 2: Customer pain points and solutions

1. Merchants face a pressured consumption environment, conservative spending willingness, and intense competition in some categories; essential categories are trending better than discretionary categories; Qwen Office E-commerce Edition connects Taobao and Tmall data, providing automation solutions for store operations, business analysis, marketing, and customer service, and supports data access from other platforms.

2. Instant retail pain points center on losses and UE; the platform improved through greater operating efficiency at Taobao Flash Sale, Freshippo's multi-format approach, and deeper cooperation; on cross-border, AliExpress revenue declined due to EU customs reform; B2B integration of international and domestic businesses connects domestic supply with overseas demand, creating a synergistic solution.

Summary 1: Platform operations and latest practices

1. The new marketing development program treats related subsidies as revenue offsets; sales and marketing expenses fell 37.83% YoY; Taobao Flash Sale investment became more efficient and operating efficiency improved; instant retail market share was solid, losses continued to narrow, and UE improved QoQ; the platform targets halving losses next year and profitability in fiscal 2029.

2. Xianyu DAU rose 23% YoY, paid orders rose 29% YoY, and it was profitable for multiple quarters; 88VIP reached about 66 million; new 88VIP ARPU rose significantly during Double 11; Qwen Office E-commerce Edition connects Taobao and Tmall data and supports cross-platform operations.

Summary 2: Merchant recruitment cooperation and trend risk avoidance

1. Freshippo deepened cooperation with Taobao Flash Sale and expanded multi-format stores to offer differentiated products to different customer groups; non-food online transaction value in instant retail rose 40% YoY; forward warehouses developed in fresh food and daily necessities; B2B international and domestic integration connects domestic supply with overseas demand.

2. The broader consumption environment is under pressure, spending willingness is conservative, and competition is intense in some categories; essential categories are trending better than discretionary categories, and the platform will strengthen the daily sales competitiveness of essential categories; AliExpress revenue declined due to EU customs reform, requiring attention to cross-border policy trends.

Summary 1: New industry developments

1. AI cloud and computing power service revenue was RMB 60.973 billion, up 53% YoY; external customer recurring revenue rose 67% YoY; AI-related product revenue was RMB 17.918 billion and grew triple digits YoY for 13 consecutive quarters; the full-stack AI upgrade covers the self-developed chip Zhenwu V900, super-node architecture, agent-native cloud infrastructure, AI models, and agents.

2. Instant retail revenue was RMB 58.757 billion, up 22% YoY; non-food online transaction value rose 40% YoY; forward warehouses developed rapidly; Taobao Flash Sale UE improved QoQ and losses narrowed, with a target of profitability in fiscal 2029.

Summary 2: Business models and new issues

1. Instant retail consists of Taobao Flash Sale, Freshippo, and Tmall Supermarket's instant delivery business; Freshippo offers differentiated products through online and offline operations and multi-format stores; Xianyu has been profitable for multiple quarters; 88VIP is about 66 million, and new-member ARPU rose during Double 11; B2B international and domestic integration connects domestic supply with overseas demand; Qwen Office E-commerce Edition connects Taobao and Tmall data and supports cross-platform operations.

2. The broader consumption environment is under pressure, spending is conservative, and competition is intense in some categories; essential categories are trending better than discretionary categories; AliExpress revenue declined due to EU customs reform, highlighting the risk that changes in cross-border policies and regulations pose to e-commerce businesses.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

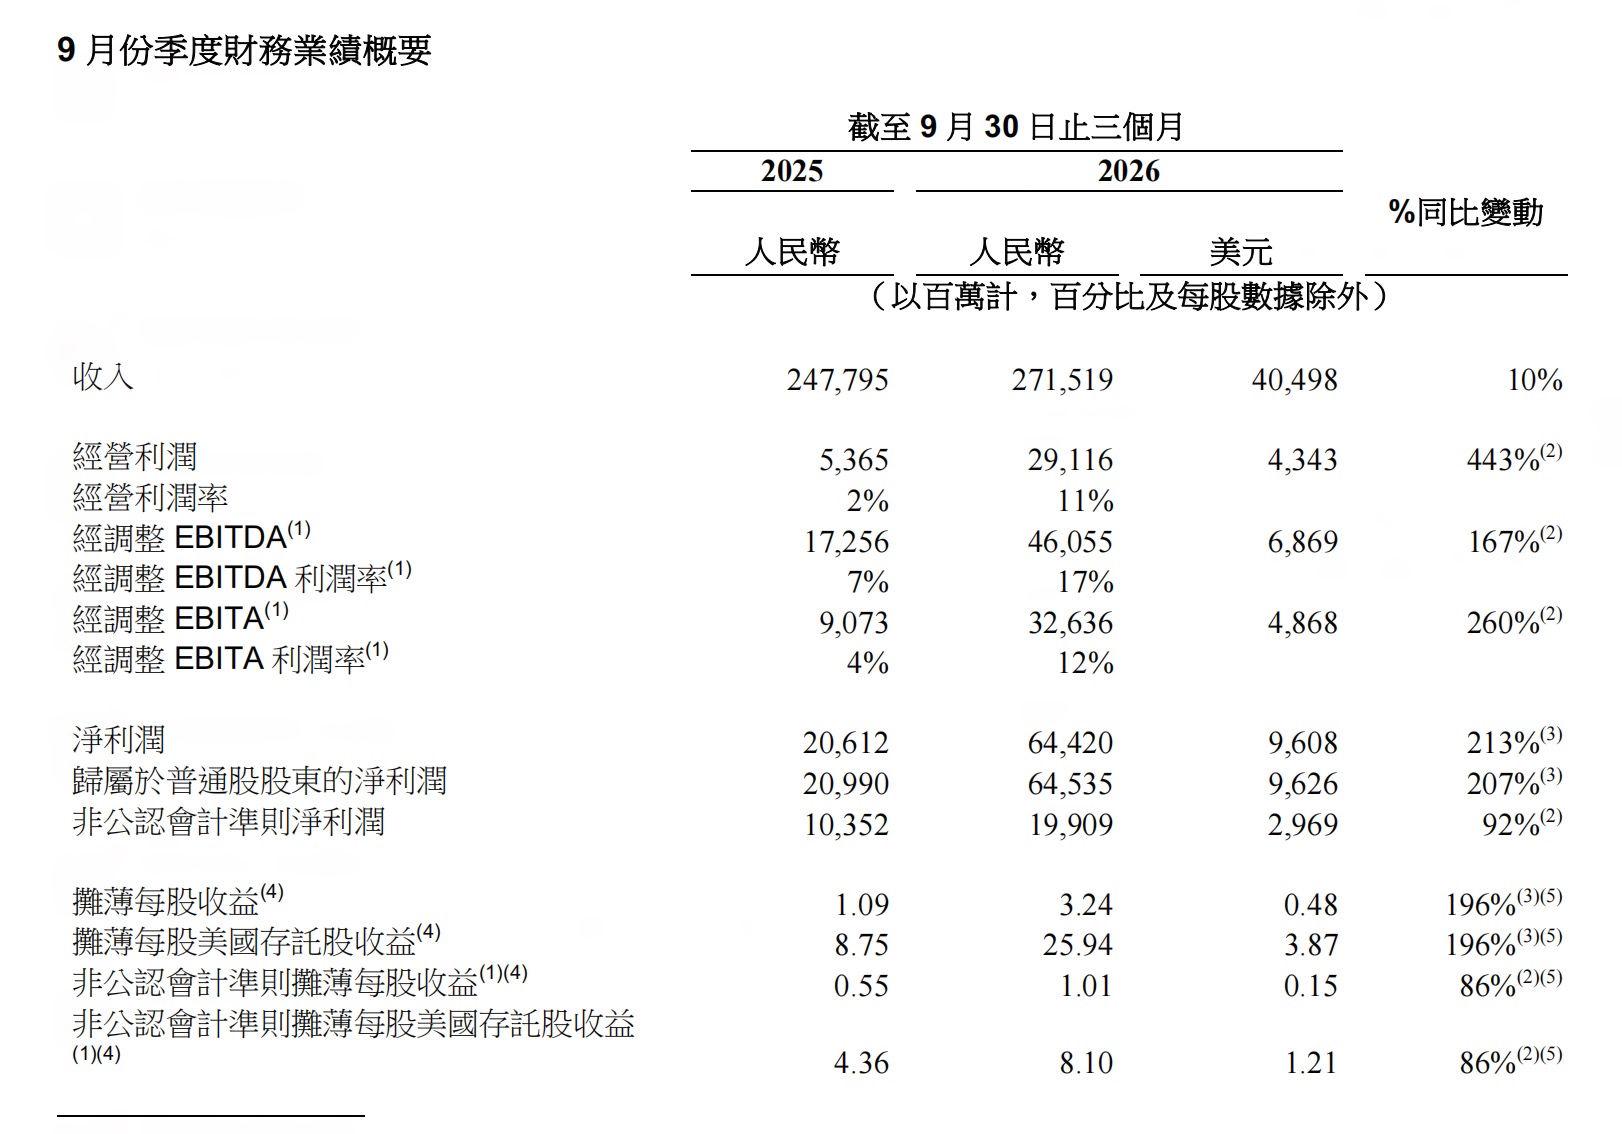
【亿邦原创】11月20日消息,阿里巴巴集团(纽交所代码:BABA港交所代码:9988)日前发布了2026年九月底止季度业绩,及截至2026年9月30日止六个月中期业绩公告。

第三季度,阿里巴巴收入达2715.19亿元(人民币,单位下同),同比增长10%。净利润为644.20亿元,同比增长213%。财报中提到,净利润的增长主要归因于投资净收益及经营利润的增加。

阿里巴巴集团首席执行官吴泳铭表示:“我们全栈AI能力持续提升商业化水平,推动本季度表现强劲。阿里云外部经常性收入增速提升至67%,带动整体云收入加速增长,盈利能力显著改善。AI相关产品收入连续第十三个季度实现三位数同比增长。我们近期公布了涵盖自研芯片、超节点架构、智能体原生云基础设施、AI模型及智能体的全面升级。其中,平头哥发布了新一代AI芯片真武V900。我们的消费业务阿里电商集团盈利显著增长,实时零售市场份额稳定且持续同比大幅减亏,我们将继续把技术创新融入全栈AI体系,以满足各行业强劲且多元的AI需求。”

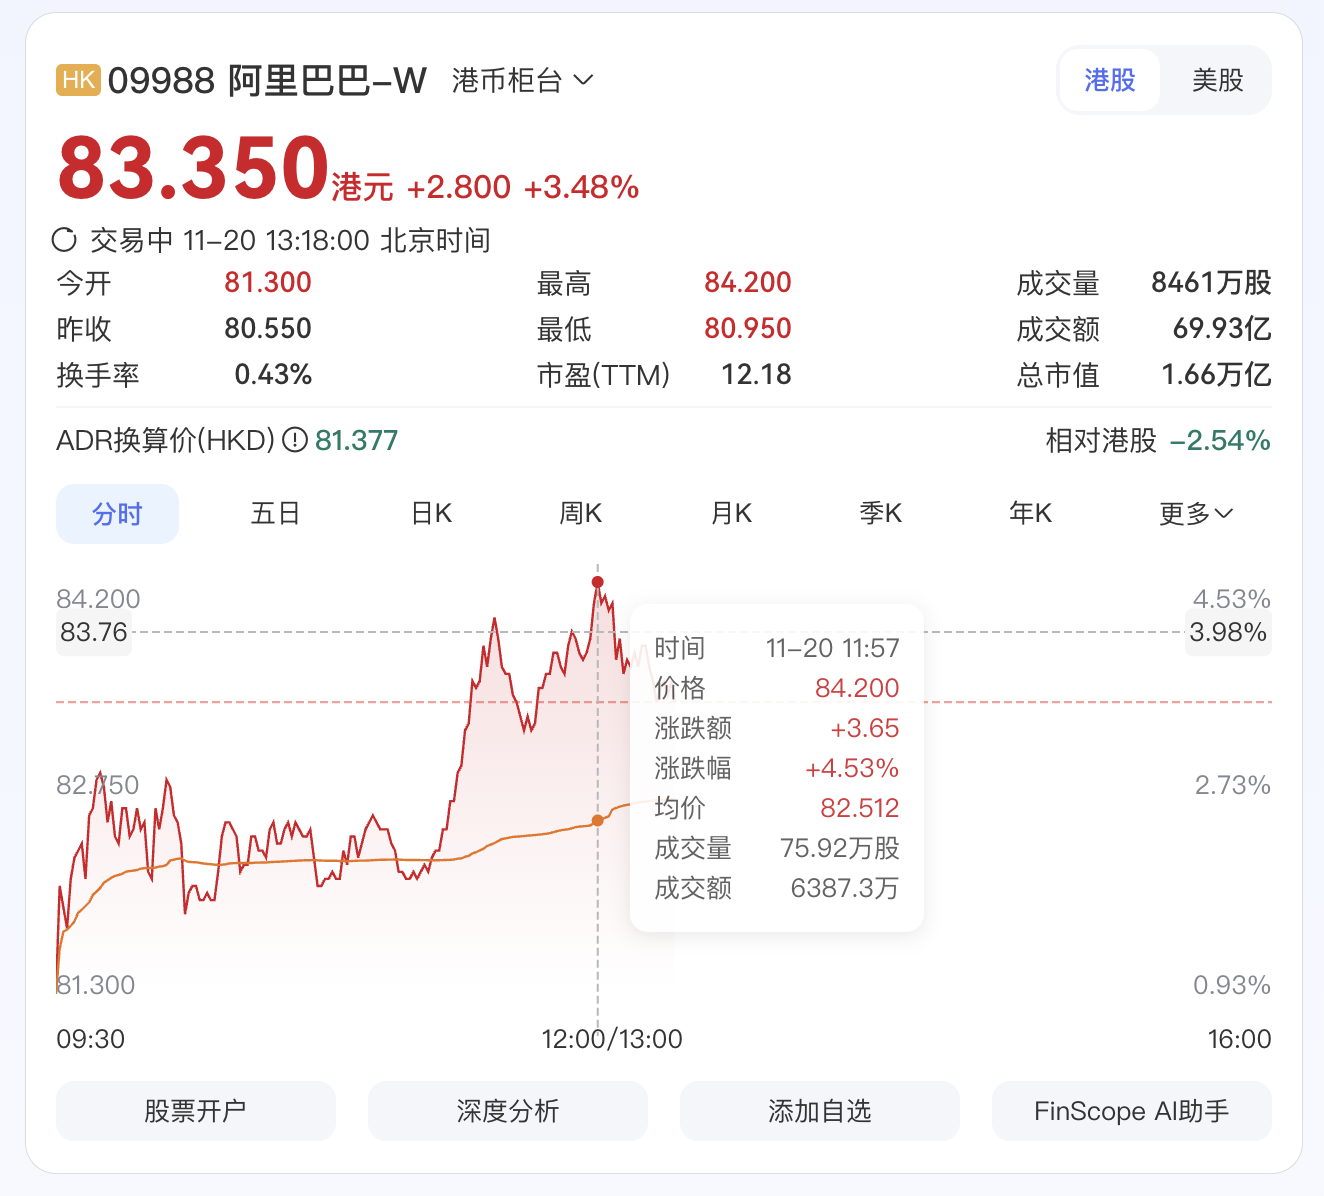
数据显示,今早港股开盘后,阿里巴巴(09988.HK)股价一度涨幅超4.5%。截至13时18分,其股价上涨3.48%,报83.350港元,成交额69.93亿元。
1.收入达2715.19亿元 净利润同比增长213%

第三季度,阿里巴巴收入为2715.19亿元,同比增长10%。净利润为644.20亿元,同比增长213%。非公认会计准则净利润为199.09亿元,同比增长92%。

报告期内,经营利润达291.16亿元,同比增长443%,主要是由于经调整EBITA的增加。经调整EBITA(一项非公认会计准则财务指标)同比增长260%至326.36亿元。该项指标的增长主要归因于淘宝闪购和云业务的经营业绩改善,以及多项业务运营效率的提升,部分被阿里巴巴对科技投入的增加所抵销。
成本表现上,截至2026年9月30日止季度,阿里巴巴营业成本为1684.76亿元,同比增长11.74%。该项成本占收入比例为62.0%,去年同时期占比60.8%。占比提升主要受云和科技业务在阿里巴巴收入结构中的占比提升,以及新营销发展计划所产生的视作收入冲减项影响所带动,部分被淘宝闪购运营效率的提升所抵销。
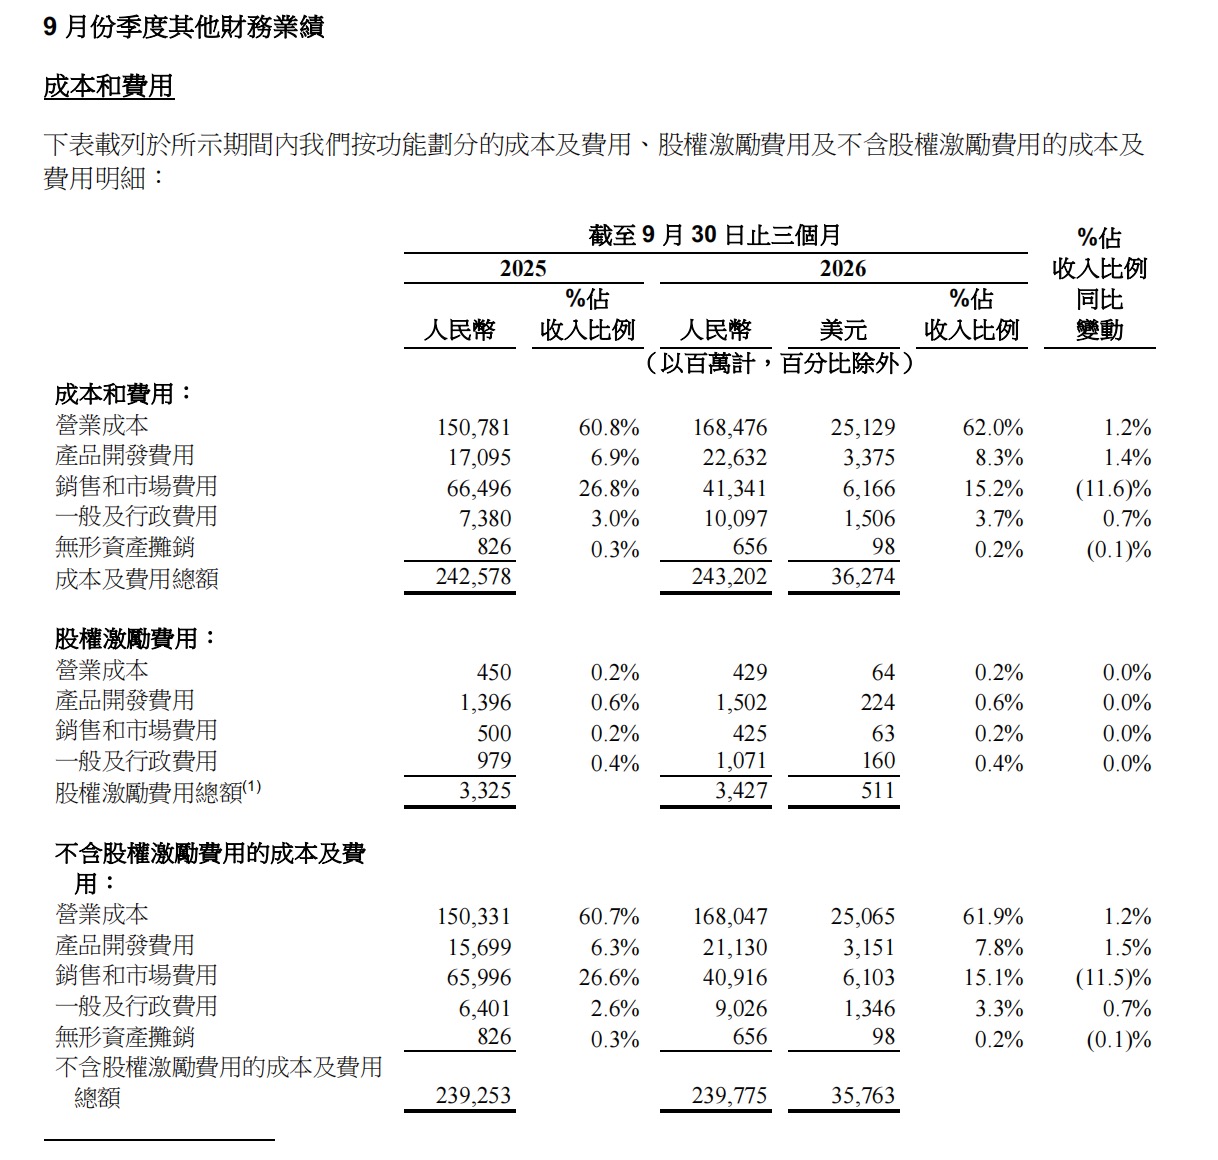
同时,销售和市场费用为413.41亿元,同比减少37.83%。该项支出占收入比例15.2%,去年同时期为26.8%。占比的下降主要是对淘宝闪购更高效的投入以及新营销发展计划的影响所致,其中先前记录为销售和市场费用的相关补贴现已视作收入冲减项。

随着阿里巴巴对技术以及研发人员的投入增加,阿里巴巴第三季度的产品开发费用为226.32亿元,同比增长32.39%,在总收入中占比8.3%,去年同时期为6.9%。

第三季度,阿里巴巴经营活动产生的现金流量净额为156.90亿元,同比增长55%。自由现金流(一项非公认会计准则财务流动性指标)为净流出344.72亿元,2025年同期为净流出218.40亿元。自由现金流的下降主要归因于阿里巴巴的云基础设施支出增加,部分被淘宝闪购亏损减少以及阿里巴巴云服务的客户预付款增加所抵销。

2.闲鱼日活跃用户同比增长23% 即时零售业务收入同比增长22%

分业务来看,财报按阿里巴巴电商集团、AI云与算力服务、AI实验室与应用以及所有其他这四个分部呈现。

财报显示,第三季度,阿里巴巴电商集团收入达1972.37亿元,同比增长2%。AI云与算力服务收入为609.73亿元,同比增长53%。外部客户收入同比增长加速至64%。外部客户经常性收入(剔除算力设备解决方案收入),同比增长67%。其中,AI相关产品收入保持强劲势头,达179.18亿元,实现连续第十三个季度的三位数同比增长。

AI实验室与应用收入达44.35亿元,同比增长51%。所有其他分部(主要包括阿里健康、虎鲸文娱集团、高德、灵犀互娱及其他科技业务)的收入为277.14亿元,同比减少5%。其中,2026年10月1日国庆假期首日,高德单日活跃用户峰值创历史新高,约3.7亿。
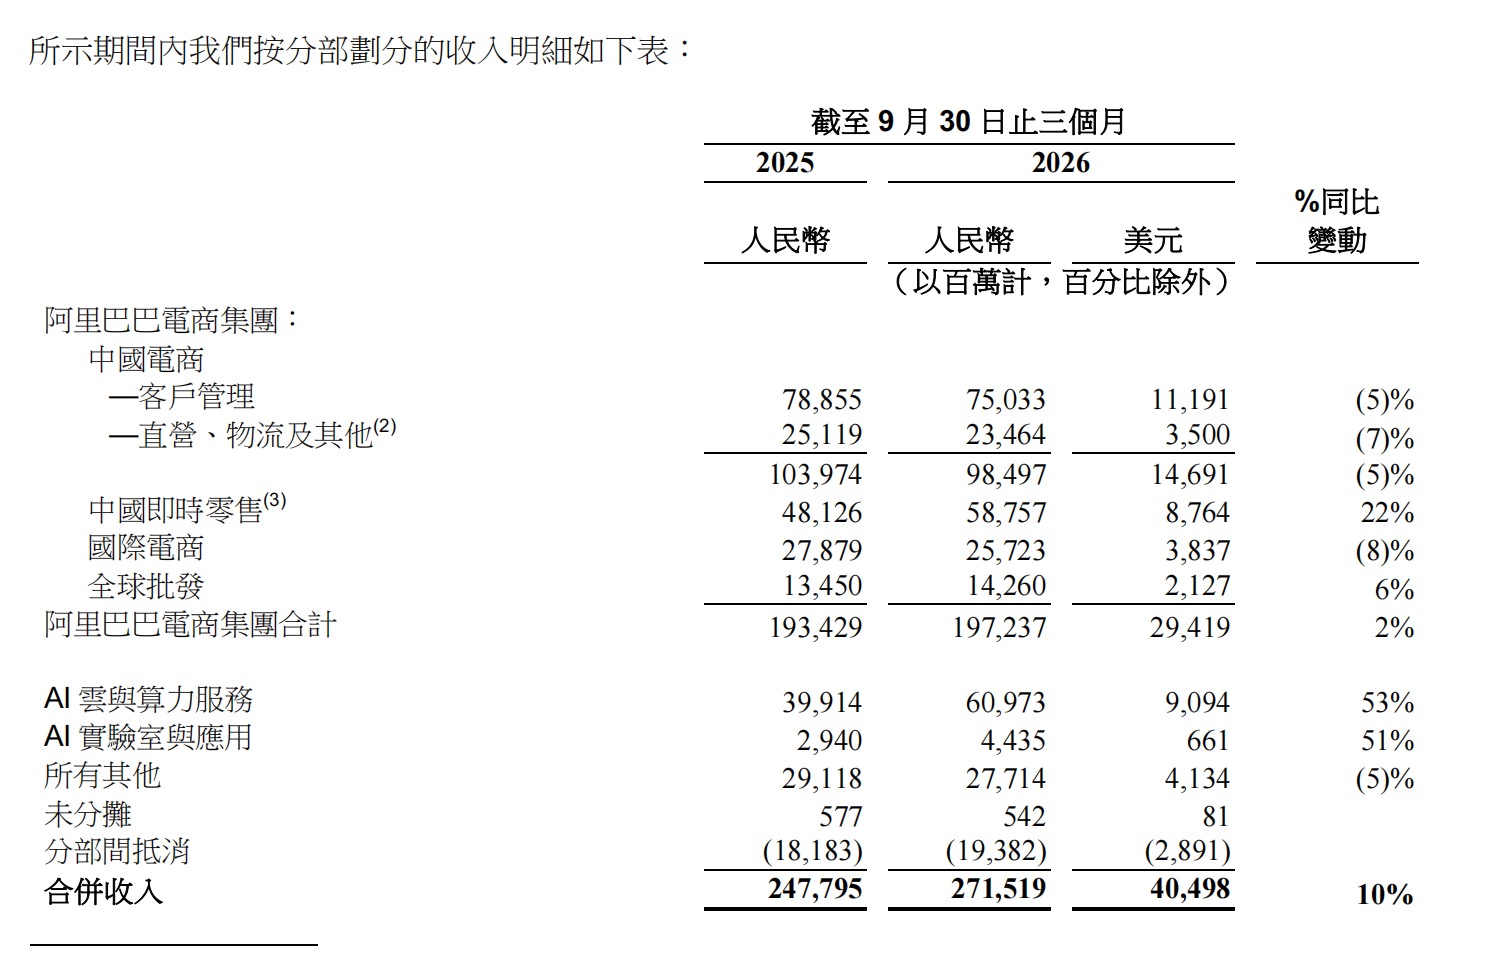
具体来看阿里巴巴电商集团的表现,阿里巴巴电商集团的收入由中国电商、中国即时零售、国际电商以及全球批发四部分组成。

第三季度,中国电商业务收入为984.97亿元,同比减少5%。其中,客户管理收入同比下降5%。若不考虑新营销发展计划所产生的视作收入冲减项影响,同口径客户管理收入同比增长将为1%。 中国电商业务下的直营、物流及其他收入主要来自天猫超市(不包含实时配送业务)、天猫国际和其他业务的直营业务 (该等业务的收入及存货成本均以总额法进行确认),以及物流服务和其他增值服务所产生的收入。直营、物流及其他收入为234.64亿元,同比减少7%。

本季度财报中还单独提到闲鱼业务的表现。财报数据显示,第三季度,闲鱼日活跃用户同比增长23%,支付订单同比增长29%,实现多季度盈利。

截至2026年9月30日止三个月,中国即时零售业务(包括淘宝闪购、盒马及天猫超市的即时配送业务)收入为587.57亿元,同比增长22%。财报中提到,该业务收入的增加主要由盒马所驱动。 盒马线上与线下渠道均保持强劲增长,得益于与淘宝闪购深化合作,以及拓展多业态门店网络,为不同客群提供差异化的产品。

国际电商业务收入达257.23亿元,同比下降8%,主要是速卖通受到欧盟海关改革影响而导致收入下降,部分被Trendyol的收入增长所抵销。

全球批发业务收入为142.60亿元,同比增长6%,主要是由于与跨境业务相关的增值服务收入增长所致。

会员方面,截至2026年9月30日,88VIP会员数量约为6600万。新88VIP会员(定义为在过去一年内成为88VIP的用户)在今年双11大促期间ARPU同比上升显著。

第三季度,阿里巴巴电商集团的经调整EBITA为388.51亿元,同比增长243%,主要是由于淘宝闪购及多项电商业务的经营表现改善所致。

财报提到,战略进展方面,阿里巴巴注重境内与跨境电商业务之间的显著协同,并深化AI能力与电商平台相结合。

业务协同方面,第三季度,阿里巴巴整合了B to B的国际与国内业务板块,打通国内供给海外需求。阿里巴巴电商事业群首席执行官蒋凡在财报电话会中指出:“在AI技术的持续加持下,我们相信投资整合也会进一步释放B to B板块更大的潜力。”

AI能力与电商平台相结合方面,10月,阿里巴巴推出面向商家的AI产品千问办公电商版。千问办公电商版旨在实现商家工作全流程的自动化,包括店铺运营、业务分析、营销和客服等环节。千问办公电商版可以直接连接淘宝与天猫的数据,并将进一步支持其他平台的数据接入,以实现更无缝的跨平台运营。

“三季度,我们整体电商板块的表现是符合预期的。国内电商保持稳定,即时零售板块在大幅减亏的情况下,依然保持非常好的同比(表现)。其他业务板块的盈利水平也明显改善。”蒋凡在财报电话会中指出,三季度、四季度以来,国内的消费大环境依然承压,消费者的支出意愿趋于保守。部分品类也一直面临着比较激烈的市场竞争。面对如此环境,四季度以来,平台的主要经营指标表现与中国实物商品网上零售的趋势一致。当前大消费的环境下,刚需品类较可选消费品类展现出更好的趋势。平台也将进一步强化刚需品类在日常销售的竞争力。

3.即时零售非餐饮部分线上交易额同比增长40%

即时零售业务的表现,是此次财报的亮点之一。无论是阿里巴巴经调整EBITA同比增长260%,还是阿里巴巴电商集团经调整EBITA同比增长243%的背后,淘宝闪购业务的经营表现改善都是重要的带动因子。

财报电话会上,阿里巴巴方面如此总结即时零售业务在第三季度的表现:即时零售市场份额保持稳固,亏损继续收窄,UE(平台单位经济模型)环比持续改善。

据蒋凡介绍,即时零售依然是未来几年平台增长的核心驱动力。具体表现上,第三季度,即时零售非餐饮部分线上交易额同比增长40%,处于领跑行业的水平。同时,前置仓业务发展迅速,在食品生鲜、日用百货等品类上,即时零售持续改变用户的消费习惯。餐饮方面,淘宝闪购的UE优化符合预期,市场份额保持稳定,比单价持续上涨。

蒋凡指出,其预计即时零售的亏损会持续缩小,阿里巴巴继续维持明年即时零售业务的亏损缩小一半的目标,并且于2029财年实现即时零售业务的盈利。

亿邦持续追踪报道该情报,如想了解更多与本文相关信息,请扫码关注作者微信。
本文首发于 亿邦动力 官方网站

【版权提示】亿邦动力倡导尊重与保护知识产权。未经许可,任何人不得复制、转载、或以其他方式使用本网站的内容。如发现本站文章存在版权问题,烦请提供版权疑问、身份证明、版权证明、联系方式等发邮件至run@ebrun.com,我们将及时沟通与处理。

已点赞

+1

{{ praise_text }}

好文章,值得被更多人看到

FAQ回顾

淘宝闪购属于阿里巴巴的哪个业务板块?

淘宝闪购属于阿里巴巴中国即时零售业务。该业务还包括盒马及天猫超市的即时配送业务。2026年第三季度,中国即时零售业务收入587.57亿元,同比增长22%,收入增加主要由盒马驱动,淘宝闪购经营表现改善则带动相关经营利润提升。

即时零售业务有哪些增长趋势?

2026年第三季度,即时零售非餐饮部分线上交易额同比增长40%,处于行业领跑水平;前置仓业务发展迅速,并在食品生鲜、日用百货等品类改变用户消费习惯。餐饮方面,淘宝闪购UE优化符合预期,市场份额稳定,比单价持续上涨。

淘宝闪购改善对阿里巴巴利润有什么影响?

淘宝闪购经营表现改善是阿里巴巴利润改善的重要带动因素。第三季度经调整EBITA同比增长260%至326.36亿元,电商集团经调整EBITA同比增长243%至388.51亿元,均与淘宝闪购及云业务、电商业务经营改善有关;销售和市场费用也因对淘宝闪购更高效投入而同比下降。

阿里巴巴即时零售业务计划何时实现盈利?

阿里巴巴计划继续收窄即时零售亏损,维持明年即时零售业务亏损缩小一半的目标,并计划在2029财年实现即时零售业务盈利。2026年第三季度,淘宝闪购经营表现改善,即时零售市场份额保持稳固,亏损继续收窄,UE环比持续改善。

阿里巴巴AI相关产品收入表现如何?

2026年第三季度,阿里巴巴AI相关产品收入达179.18亿元,连续第十三个季度实现三位数同比增长;AI云与算力服务收入609.73亿元,同比增长53%,外部客户经常性收入同比增长67%。这体现全栈AI能力商业化水平提升。

广告

下一篇

征集报名《品牌数字化服务商资源手册》

《品牌数字化服务商资源手册》展示数字化服务商风采,亿邦全年零售大会通发,触达更多资源,马上加入!

马上入驻

小派科技黑五目标业绩翻倍 Dream Air系列新品迎来首战|黑五微访谈

正值年末大促季,亿邦动力特别策划“拼重力·2026跨境电商黑五旺季”专题,邀请出海品牌和服务商展开系列访谈,探讨企业如何应对市场竞争变化、布局黑五旺季,并将大促流量转化为长期品牌价值。

品牌故事 VR一体机 跨境电商

2026-11-20 11:53:39