



• 亿邦公众号
    • APP下载

平台霸权之下,电商人怎么活?

作者:龚作仁 文章来源:Laborer

2026-06-15 17:47

作者:龚作仁 文章来源:Laborer

2026-06-15 17:47

邦小白快读
EN
全文速览

本文核心是指出当前纯电商模式已经走向尾声,平台霸权下商家普遍陷入困境,分享了电商人破局自救的四个实操方向:

1. 主动应用AI重塑企业竞争力,AI是绕不开的时代浪潮,作者已经在茵曼、初语等品牌全面落地AI,实现了降本增效,效果相当于额外多卖3亿货物才能获得的利润,普通从业者必须主动学习用AI提升生产力。

2. 布局线下新实体打造护城河,作者2015年布局线下,如今茵曼拥有600多家线下店,实现线上线下多元布局,避免把命运交给单一渠道,新店可同时搭配直播店、私域店,配套保姆式赋能,实体店是对抗算法霸权的底盘。

3. 抓住即时零售风口,把门店做成离消费者最近的配送节点,享受30分钟到家的效率红利。

4. 打造自有IP矩阵,老板和店主都可以下场做IP,掌握自有流量,穿透算法屏蔽,已有案例靠做IP实现年销从4万涨到2000万。

当前纯电商品牌普遍被困在平台算法中,沦为给平台交租的数字店农,平台的低价内卷规则剥夺了品牌定价权,抹杀了品牌长期积累的价值,品牌还陷入七高困境,没有空间投入研发创新,针对品牌破局给出以下方向:

1. 渠道建设层面,必须摆脱单一平台依赖,布局线下新实体打造护城河,打造“实体店+直播店+私域店”的三合一业态,既可以做销售体验,还可以作为即时零售的前置配送节点,是品牌跨越周期的底气。

2. 降本增效层面,要全面落地AI重构核心竞争力,AI可以帮助品牌实现可观的降本增收,作者的品牌落地AI后,获得了相当于额外3亿销售额的利润增益。

3. 品牌营销层面,要打造自有IP矩阵,老板亲自下场做IP可以建立消费者信任,穿透算法屏蔽,还可以对接供应链资源,终端店主做IP也能撬动巨大增量,帮助品牌掌握自有流量。

当前消费趋势已经转向30分钟即时配送,品牌需要提前布局抓住红利。

当前纯电商旧模式已经走到尽头,平台霸权下卖家普遍面临七高风险,纯靠平台流量硬扛只会逐渐被淘汰,本文给卖家总结了风险提示和破局机会:

1. 风险提示:纯线上单渠道经营,完全依附平台会丧失定价权和流量自主权,最终会被高流量成本、低价内卷挤压掉所有利润,陷入亏损困局。

2. 新增量机会:可以从四个方向布局破局,分别是AI降本增效、新实体布局、即时零售、IP矩阵,这四个方向是未来电商增长的新赛道。

3. 实操可落地的机会:布局线下实体店的时候,可以同步做线上直播店和私域店,一地多用,既分散渠道风险,还能作为即时零售的前置仓拿到效率红利。

4. 流量机会:不管是老板还是终端店主,都可以下场做自有IP,把平台的公域流量转化为自己可控的私域流量,已有案例靠做IP实现年销从4万涨到2000万,还能通过IP轻松对接优质供应链资源。

当前电商行业正在发生整体性变革,给工厂带来了新的商业机会,也给出了数字化转型的启示:

1. 商业合作机会:品牌端正在转型,多渠道布局和IP化运作,对优质、稳定的供应链需求大幅提升,很多品牌会通过公开IP对接供应链,工厂可以主动对接品牌IP获得合作机会,比如茵曼老方只发了一条找童装供应链的视频,就吸引了上百家工厂对接,最终10多家工厂达成了稳定合作。

2. 数字化转型启示:品牌端已经开始全面应用AI实现降本增效,工厂也需要主动拥抱AI,用AI优化生产、设计环节,降低自身运营成本,提升核心竞争力,适应下游品牌的转型需求。

3. 自身转型启示:工厂也可以参考品牌的转型路径,摆脱对单一渠道大客户的依赖,布局自己的线上线下渠道,打造自有IP掌握用户和流量,分散经营风险,抓住新的增长机会,新实体和即时零售的发展也带动了品牌线下扩张,工厂可以对接品牌需求拿到更多稳定订单。

当前电商行业整体陷入平台霸权下的增长困境,催生了大量新的商家痛点和服务需求,给服务商带来了新的发展方向:

1. 商家核心痛点:当前绝大多数电商商家都面临七高问题,分别是高退货、高付费流量成本、高人工、高供应链成本、高平台比价、高库存损耗、高合规成本,利润被平台和上下游完全挤压,商家迫切需要能够降本增效、摆脱平台依赖的解决方案。

2. 行业发展趋势:商家已经集体开始向四个新方向转型,分别是AI应用落地、线下新实体布局、即时零售链路打通、自有IP矩阵打造,整个行业的转型创造了大量的服务缺口。

3. 服务商的机会点:服务商可以围绕商家转型的四个方向开发对应服务产品,比如AI落地培训、新实体门店运营赋能、即时零售履约对接、IP孵化运营等,针对中小电商卖家转型的赋能服务会成为新的高增长赛道,满足商家重构组织能力、转型新模式的需求。

当前主流电商平台的现有模式已经引发商家集体不满,暴露了很多问题,也给平台未来发展带来很多启示:

1. 商家对现有平台的核心诉求和不满:现有平台掌握流量、数据和规则制定权,通过算法引导低价内卷,不断挤压商家利润,剥夺商家的定价权,抹杀商家长期积累的品牌价值,导致商家沦为给平台交租的数字店农,绝大多数商家陷入七高亏损困境,商家普遍有摆脱单平台依赖的倾向。

2. 现有模式的风险:如果平台持续维持现有规则,不断挤压商家生存空间,会导致大量商家外流,流向线下新实体、自有IP、私域等新渠道,最终平台会失去商家和供给资源,影响长期发展。

3. 平台可调整的方向:可以调整流量规则和比价机制,降低商家流量成本,保护商家的定价权和品牌积累,同时围绕商家转型AI、新实体、即时零售的需求推出对应的扶持服务和流量政策,吸引商家留在平台,还可以提前布局即时零售赛道,对接线下实体资源,抓住新的增长风口。

当前中国电商产业已经进入新的发展阶段,旧的纯平台电商模式已经走向尾声,出现了很多新问题和新探索,对产业研究有很高的价值:

1. 产业出现的新问题:头部平台垄断流量和规则制定权,形成平台霸权,纯电商商家被困在算法系统中,低价内卷导致全产业链利润被过度挤压,不仅商家生存困难,还带来了高退货、高库存损耗等社会资源浪费问题,同时也抑制了企业研发创新的动力,不利于产业长期升级。

2. 产业新动向和新探索:业内头部商家已经开展了四种新商业模式的探索,分别是AI驱动降本增效的组织升级模式、线上线下融合的新实体模式、依托线下门店的即时零售模式、自有IP掌握流量的IP矩阵模式,这些都是商家对抗平台霸权、自主掌握命运的创新实践。

3. 对政策研究的启示:如何规范平台行为,避免平台霸权挤压中小商家生存空间,鼓励多元电商业态创新发展,是当前产业政策需要研究解决的新问题,这些商家的自主破局探索也为产业转型提供了宝贵的实践样本。

声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article argues that the era of pure e-commerce has come to an end, with most merchants trapped in a difficult position under platform dominance. It outlines four actionable strategies for e-commerce players to break out of this predicament:

1. Proactively adopt AI to reshape corporate competitiveness. As an inevitable industry trend, AI has been fully implemented across the author’s brands including Inman (Yinman) and Chuyu, driving cost reduction and efficiency gains equivalent to the profit that would come from an additional ¥300 million in sales. Ordinary industry practitioners must learn to leverage AI to boost productivity.

2. Build offline new retail outlets to create a competitive moat. The author began expanding offline in 2015, and Inman now operates more than 600 brick-and-mortar stores. This hybrid online-offline layout prevents merchants from leaving their fate to a single channel; new stores can operate as combined live retail outlets and private domain shops, supported by full-stack enabling services. Physical stores serve as a solid foundation to counter algorithmic dominance.

3. Capitalize on the on-demand retail boom, turning stores into the closest delivery nodes to consumers to capture the efficiency dividend of 30-minute delivery.

4. Build an in-house IP matrix. Both brand owners and store owners can build their own IPs to control independent traffic and bypass algorithmic blocking. One existing case saw annual sales surge from ¥40,000 to ¥20 million after launching an IP strategy.

Most pure e-commerce brands are currently trapped by platform algorithms, reduced to "digital tenant farmers" paying rent to platforms. Platforms’ low-price cutthroat competition rules have stripped brands of their pricing power and erased long-term accumulated brand value. Brands are also stuck in the "seven highs" predicament, leaving no room for R&D and innovation. This article outlines the following paths for brands to break out:

1. For channel development: Brands must end dependence on a single platform, build offline new retail to form a competitive moat, and develop a three-in-one business model combining physical stores, live-stream stores and private domain shops. This model not only supports sales and customer experience but also serves as front-end delivery nodes for on-demand retail, providing resilience to navigate industry cycles.

2. For cost reduction and efficiency improvement: Fully implement AI to rebuild core competitiveness. AI delivers considerable cost cuts and revenue growth for brands; the author’s own brands have achieved profit gains equivalent to an additional ¥300 million in sales after AI adoption.

3. For brand marketing: Build an in-house IP matrix. When brand owners build their own IPs, they earn consumer trust, bypass algorithmic blocking, and connect with supply chain resources. Store owner IPs can also unlock massive incremental sales, helping brands control their own traffic.

Brands should prepare early to capture the dividend of the fast-growing 30-minute on-demand delivery trend.

The old pure e-commerce model has reached its end, and most sellers face "seven highs" risks under platform dominance. Relying solely on platform traffic will only lead to gradual elimination. This article summarizes risk warnings and breakout opportunities for sellers:

1. Risk warning: Operating only on a single online channel and relying entirely on platforms strips sellers of pricing power and traffic autonomy. Ultimately, high traffic costs and cutthroat low-price competition will squeeze out all profits, leaving sellers trapped in losses.

2. Incremental growth opportunities: Sellers can pursue breakout through four key directions: AI-driven cost reduction and efficiency, new physical retail layout, on-demand retail, and IP matrix building. These four areas are the new growth tracks for the future of e-commerce.

3. Actionable opportunities: When laying out offline physical stores, sellers can simultaneously operate online live-stream stores and private domain shops to maximize use of space. This disperses channel risk and allows sellers to capture efficiency dividends by serving as front-end warehouses for on-demand retail.

4. Traffic opportunities: Both brand owners and frontline store owners can build their own IPs to convert platform public traffic into controllable private traffic. One existing case saw annual sales jump from ¥40,000 to ¥20 million through IP building, and IPs also make it easier to connect with high-quality supply chain resources.

The e-commerce industry is undergoing overall transformation, bringing new business opportunities and insights for factories’ digital transformation:

1. Business partnership opportunities: As brands transform through multi-channel layout and IP-based operations, demand for high-quality, stable supply chains has risen sharply. Many brands now source supply chain partners via their public IP channels. Factories can proactively connect with brand IPs to secure cooperation. For example, when the founder of Inman posted a single video looking for children’s clothing supply chains, it attracted more than 100 factories, and 10 eventually secured long-term stable cooperation.

2. Insights for digital transformation: Brands have begun full-scale AI adoption to cut costs and improve efficiency. Factories should also proactively embrace AI, using it to optimize production and design, reduce operating costs, boost core competitiveness, and meet the transformation needs of downstream brands.

3. Insights for self-transformation: Factories can also follow brands’ transformation paths to end dependence on large single-channel clients, build their own online and offline channels, develop in-house IPs to control users and traffic, diversify operational risks, and capture new growth opportunities. The growth of new physical retail and on-demand retail has driven brands’ offline expansion, allowing factories to secure more stable orders by meeting brands’ demand.

The overall e-commerce industry is stuck in a growth predicament under platform dominance, giving rise to a host of new merchant pain points and service demand, opening up new development directions for service providers:

1. Core merchant pain points: The vast majority of e-commerce merchants face seven high costs: high return rates, high paid traffic costs, high labor costs, high supply chain costs, high platform price comparison pressure, high inventory损耗, and high compliance costs. Profits are completely squeezed out by platforms, upstream and downstream players, and merchants urgently need solutions that can cut costs, improve efficiency, and help them end platform dependence.

2. Industry development trends: Merchants are collectively shifting toward four new directions: AI implementation, offline new physical layout, on-demand retail link integration, and in-house IP matrix building. This industry-wide transformation has created massive unmet service demand.

3. Opportunities for service providers: Service providers can develop targeted service products around the four transformation directions, such as AI implementation training, new physical store operation enablement, on-demand retail fulfillment connection, and IP incubation and operation. Enablement services for small and medium-sized e-commerce sellers’ transformation will emerge as a new high-growth track, meeting merchants’ demand for rebuilding organizational capabilities and transitioning to new business models.

The existing model of mainstream e-commerce platforms has triggered widespread discontent among merchants, exposed major flaws, and offered key insights for platforms’ future development:

1. Merchants’ core grievances and demands: Existing platforms control traffic, data, and rule-setting power, use algorithms to encourage low-price cutthroat competition, continuously squeeze merchant profits, strip merchants of pricing power, and erase long-term accumulated brand value, reducing merchants to "digital tenant farmers" paying rent to platforms. The vast majority of merchants are trapped in the "seven highs" loss predicament and generally seek to end single-platform dependence.

2. Risks of the existing model: If platforms continue to maintain current rules and squeeze merchants’ living space, a large number of merchants will exit and move to new channels such as offline new physical retail, in-house IPs, and private domains. Ultimately, platforms will lose merchants and supply resources, undermining their long-term development.

3. Potential adjustments for platforms: Platforms can adjust traffic rules and price comparison mechanisms to lower merchants’ traffic costs, protect merchants’ pricing power and accumulated brand value. They can also launch targeted support services and traffic policies aligned with merchants’ transformation needs in AI, new physical retail, and on-demand retail to retain merchants. They can also lay out the on-demand retail track early, connect with offline physical resources, and capture the new growth boom.

China’s e-commerce industry has entered a new development stage, and the old pure-platform e-commerce model has reached its end. The emergence of new problems and new exploratory practices offers high value for industrial research:

1. New industry problems: Leading platforms monopolize traffic and rule-setting power, forming platform dominance. Pure e-commerce merchants are trapped in algorithmic systems, and low-price cutthroat competition has led to excessive profit compression across the entire industrial chain. This has not only made merchant survival difficult but also created social waste such as high return rates and excessive inventory损耗, while suppressing enterprises’ motivation for R&D and innovation, which is not conducive to long-term industrial upgrading.

2. New industry trends and exploratory practices: Leading industry merchants have already tested four new business models: AI-driven organizational upgrading for cost reduction and efficiency, online-offline integrated new physical retail, on-demand retail anchored in offline stores, and traffic control via in-house IP matrices. All these are innovative practices for merchants to counter platform dominance and take control of their own destiny.

3. Insights for policy research: How to regulate platform behavior, prevent platform dominance from squeezing small and medium-sized merchants’ living space, and encourage innovative development of diverse e-commerce formats is a new issue that industrial policy needs to address. These bottom-up breakout efforts by merchants also provide valuable practical samples for industrial transformation.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

最近,和不少电商企业老板聊天,听到最多的一个字就是:难。大家拼命搞业绩,利润却像沙子一样从指缝漏掉。从本质上看,纯电商的模式,实际上已经走向了时代尾声。这不是危言耸听!

十几年前,互联网平台确实是赋能者,帮我们拆掉地域墙、抹平信息差,让小卖家、小老板也能把货卖到全国,那是电商的黄金时代。

今天,台子还是那个台子,庄家却变了。

流量是平台的、数据是平台的,交易规则也是平台定的,只要停了推广费,流量立马哗啦啦往下掉。

表面上在电商平台创业,实际上我们都被困在了系统的算法里,成了给平台交租的“数字店农”。

现在平台的经营抓手只有四个字:低价内卷。你不降价,流量就腰斩,商家在赔本赚吆喝。导致的结果是商家、消费者、服务商都在给平台打工,甚至还造成巨大的社会资源浪费。

这种生态持续下去,谈何搞研发、做创新?

看看现在,割在电商企业身上的“七把刀”,每一刀都在要老板们的命:

第一,高退货。女装退货率仍然居高不下,已经飙到70%-90%。货发出去了,钱收不回来。有媒体算过账,一笔退货商家要倒贴约15元,退货率40%的话,做1000万销售至少亏30万。

第二,高付费。平台的比价一年比一年狠,流量成本吃掉了大家原本就微薄的利润,我身边服装电商的老板们也个个深痛无奈,ROI越做越低。

第三,高人工。工资、社保连年涨,组织管理内耗极大,很多老板在算账—成本和卖货的毛利之间的平衡,这样如何稳就业、稳岗位?

第四,高成本。原材料、包装耗材等供应链成本都在涨,但平台比价逼着你不敢涨价,利润被两端挤压得干干净净。

第五,高比价。消费者在线上刚下单,平台马上给TA弹出一个便宜一半的同款。商家完全丧失了定价权,品牌投入和积累被抹杀殆尽。

第六,高损耗。库存积压成了常态,退回来的衣服有的领口带口红印、有的浓浓香水味,根本无法二次销售。赚的都在仓库里,亏的全是真金白银。

第七,高税费。合规成本上升是必然,但短期内确实挤压了生存空间,很多中小老板每天都在提心吊胆做账。同时,我更认为合规是每家企业,都要迎难而上的必然选择,阳光大道才是坦途。

在这“七高”的绞杀下,电商早就成了利润最薄的传统行业。如果还按老路子硬扛,就是温水煮青蛙,只是早被干跨,还是晚被干跨而已。

谁能带电商人走出死胡同?

我认为只有自己救自己!

我做实业快30年,经历5次生死周期,活到今天。大多数时间都在“晴天修屋顶”、深知“好的光景都不太长”,我们也在不断迭代组织和商业结构。

第一,AI是生死线。

不会用AI的人,未来一文不值。

这是绕不开的时代浪潮。很多人看到AI抢饭碗,我的总结是—Ai将重塑一家企业的核心竞争力。今年我们在茵曼、初语等品牌全面应用Ai,也取得了一些降本增效的实效。按常规利润率算,额外多卖3个亿的货才能赚得回来。我是逼着自己和团队上手,把AI变成了生产力。

第二,新实体。

没有线下护城河,纯线上品牌活不过五年

2015年我坚决走到线下开店,亏了上千万买教训,也换来了一条生路:今天茵曼在全国有600多家店,形成了线上线下“四分天下”,不至于把命交在单一渠道上。

现在我们开一家实体店,不仅做店铺内销售,还送一家直播店、一家私域店,提供培训、物流、售后全保姆式赋能。

实体店一定是品牌跨越周期的底盘,是你对抗算法霸权的底气。

第三,即时零售。

门店是品牌信任触点和增值服务中心

30分钟万物到家的时代已经来了。电商如何利用线下资产提升履约效率?门店不只是体验中心,它更是离消费者最近的配送节点。谁先打通这一步,谁就能吃到下一波效率红利。

第四,IP矩阵

摆脱流量依赖,老板要敢于站出来

前阵子我买了台追觅的洗衣机放办公室。以前在商场看到他们的店,我以为是杂牌根本没进去。直到看到他们老板每天发视频,我才对品牌建立信任,一买发现还不错。

这就是IP的力量,它能穿透算法的屏蔽。像我,快50岁的人自己也下场做了视频号IP(茵曼老方)。我们做童装缺供应链,发了一期视频,吸引了100多家供应商来谈,最终稳定合作了10多家。

还有我们婺源店一位46岁的店主,以前一个月才卖4万块,差点被淘汰。

后来她听劝做起IP账号直播,去年一年卖了2000万!今年还带出了五六个新主播。成功实现被平台分发流量,到自己掌握流量生意。

这四条路,每一条单走都不容易,它需要你重构组织的DNA。关键在于,你敢不敢下场?有没有壮士断腕的魄力?

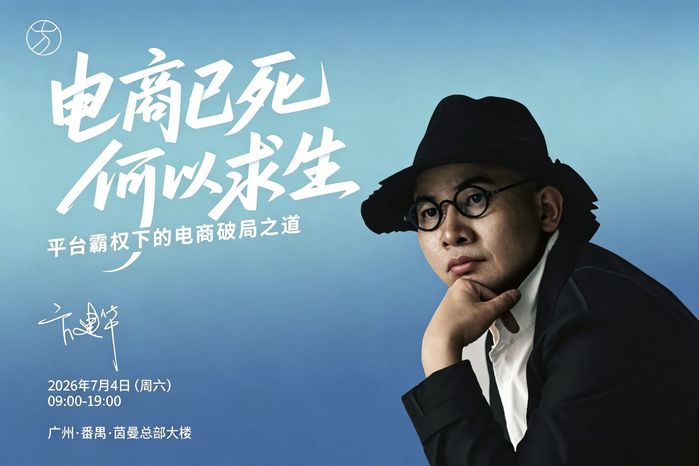
7月4号,我将在广州办一场电商人粉丝会

主题谈《新时代下,电商生存之道》

我想和还在坚守的电商老板们,关起门来聊聊怎么破局求生,怎么抓住下一个时代的机遇。

电商的旧模式已死,但做电商的老板,绝不能死在这个冬天

7月4号,我们广州见。—茵曼老方
注:文/龚作仁,文章来源:Laborer,本文为作者独立观点,不代表亿邦动力立场。

【版权提示】亿邦动力倡导尊重与保护知识产权。未经许可,任何人不得复制、转载、或以其他方式使用本网站的内容。如发现本站文章存在版权问题,烦请提供版权疑问、身份证明、版权证明、联系方式等发邮件至run@ebrun.com,我们将及时沟通与处理。

已点赞

+1

{{ praise_text }}

好文章,值得被更多人看到

广告

下一篇

跨境电商资源对接

《全球跨境电商服务商资源手册》第二期手册现已发布,触达更多资源,了解跨境服务商信息,欢迎点击链接下载。

了解详情

复利效应:XbotGo如何从线上直营攻入Best Buy

在马蹄社CEO刘宸与XbotGo创始人谈科峰的对话中,谈科峰系统地阐述了公司在产品被验证后的增长逻辑。

跨境电商

2026-06-15 16:34:48











